Minnesota’s Medicare Advantage market is undergoing major changes for 2027.
According to an October 1 report from the Minnesota Star Tribune, more than 320,000 Minnesotans are enrolled in Medicare Advantage plans that are being discontinued for 2027.
Blue Cross and Blue Shield of Minnesota, HealthPartners, Medica, UnitedHealthcare and Humana are among the insurers making significant changes.
For many Minnesota Medicare beneficiaries, this year’s Medicare review isn’t optional.
availability varies by county. A plan available in one Minnesota county may not be available in another.
More Than 320,000 Minnesotans Are Affected
The Minnesota Star Tribune reports that more than 320,000 Minnesotans are enrolled in Medicare Advantage plans being eliminated for 2027.
The changes involve several of Minnesota’s major Medicare insurers.
Blue Cross and Blue Shield of Minnesota
Blue Cross is making the largest changes.
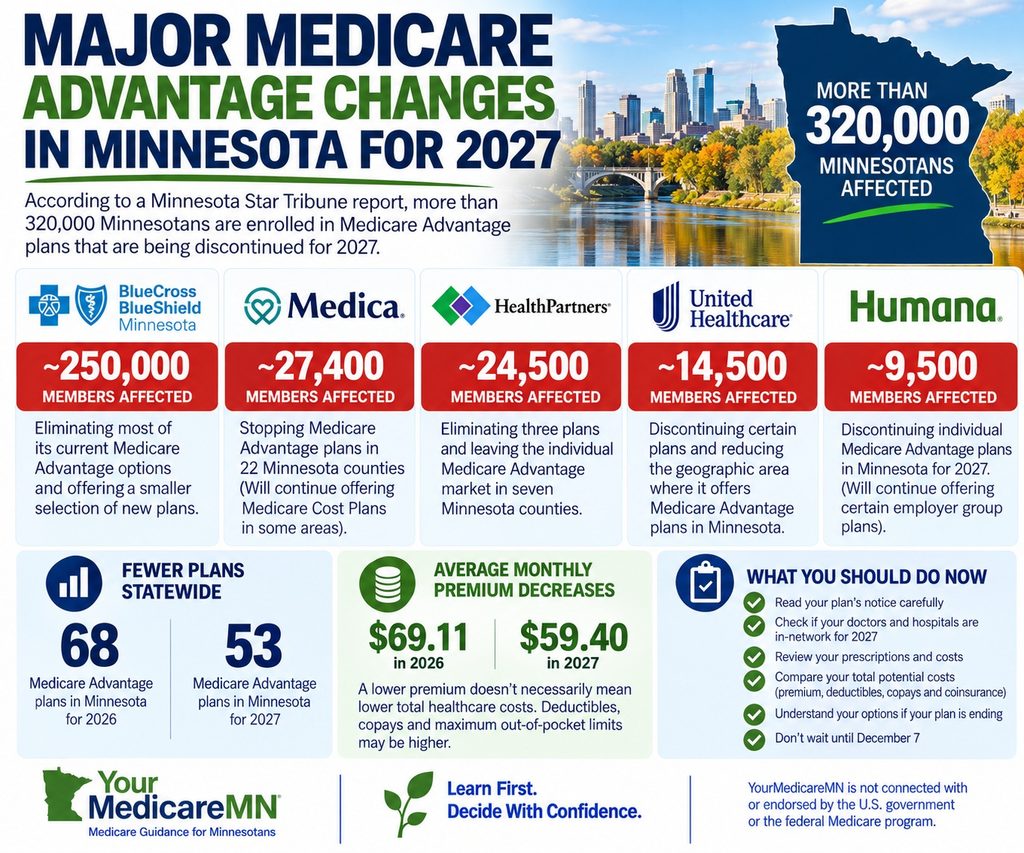
According to the Star Tribune, approximately 250,000 Blue Cross members are receiving notices related to plans that are ending.
Blue Cross is eliminating most of its existing Medicare Advantage options and replacing some of them with a smaller selection of new plans.
The effect depends heavily on where you live.
In some counties, new Blue Cross Medicare Advantage plans will be available.
In other counties, Blue Cross will no longer offer individual Medicare Advantage coverage for 2027.
Medica
Medica is also reducing its Medicare Advantage footprint.
The Star Tribune reports that approximately 27,400 Medica members will need to select new coverage.
Medica will stop offering Medicare Advantage plans in 22 Minnesota counties, although Medicare Cost Plans will be available from Medica in some areas.
HealthPartners
HealthPartners is also reducing its Medicare Advantage offerings.
Approximately 24,500 HealthPartners members are affected by plans being discontinued.
The company is eliminating three plans and leaving the individual Medicare Advantage market entirely in seven Minnesota counties.
UnitedHealthcare
UnitedHealthcare is discontinuing certain Medicare Advantage plans and reducing the geographic area where it offers plans in Minnesota.
According to the Star Tribune, approximately 14,500 Minnesota members are affected.
Humana
Humana is taking an even larger step.
For 2027, Humana is discontinuing its Medicare Advantage plans sold to individuals in Minnesota.
Approximately 9,500 members are affected.
Humana will continue offering Medicare Advantage coverage through certain employer group arrangements, but it will no longer offer individual Medicare Advantage plans in Minnesota for 2027.
Fewer Plans Doesn’t Mean No Medicare Advantage
It’s important to put these changes in perspective.
Medicare Advantage is not disappearing from Minnesota.
The Centers for Medicare & Medicaid Services reports that 53 Medicare Advantage plans will be available somewhere in Minnesota for 2027, compared with 68 in 2026.
The federal government also reports that 100% of Minnesota Medicare beneficiaries will have access to at least one Medicare Advantage plan in 2027.
However, that doesn’t mean every beneficiary has 53 plans available.
Medicare Advantage availability is based on where you live.
Your actual choices depend on your county and, in some cases, your specific service area.
Why Are Insurance Companies Making These Changes?
The insurers cited in the Star Tribune report point to increasing healthcare utilization and rising medical and prescription drug costs.
Blue Cross and Blue Shield of Minnesota reported significant financial losses in its Medicare Advantage business in recent years.
Medica similarly cited higher medical and prescription drug costs and increased use of healthcare services.
HealthPartners said it was reducing its Medicare Advantage portfolio in an effort to continue offering sustainable Medicare options in the future.
These changes are part of a broader restructuring of the Medicare Advantage market, but the impact is particularly noticeable in Minnesota for 2027.
A Lower Premium Doesn’t Necessarily Mean Lower Healthcare Costs
Here’s one of the most important things to understand about the 2027 changes.
The Centers for Medicare & Medicaid Services projects that Minnesota’s average Medicare Advantage monthly plan premium will actually decrease, from $69.11 in 2026 to $59.40 in 2027.
At first glance, that sounds like Medicare Advantage is becoming less expensive.
But premium is only one part of what Medicare coverage costs.
The Star Tribune’s analysis found that many Minnesotans may face higher costs when they actually use healthcare.
Those costs can include:
- Deductibles
- Primary care and specialist copays
- Hospital copays
- Coinsurance
- Maximum out-of-pocket limits
- Prescription drug costs
This is why comparing Medicare Advantage plans based solely on the monthly premium can be misleading.
The premium tells you what it costs to have the plan.
Cost-sharing tells you what you may pay when you use it.
You need to consider both.
Maximum Out-of-Pocket Limits Deserve Particular Attention
One of the more significant changes reported for 2027 involves maximum out-of-pocket limits.
A Medicare Advantage plan’s maximum out-of-pocket limit places an annual cap on qualifying cost-sharing for covered Medicare Part A and Part B services.
According to the Star Tribune’s analysis, the median maximum out-of-pocket limit for in-network Medicare Advantage care in Minnesota is increasing from approximately $5,000 in 2026 to $6,900 in 2027.
Individual plans can be significantly different.
For example, the Star Tribune reports that in Hennepin County, Blue Cross is eliminating its current Medicare Advantage plans that include prescription drug coverage and replacing them with one new option.
The existing plans have in-network maximum out-of-pocket limits ranging from $3,400 to $5,900.
The new 2027 option reportedly has an in-network maximum out-of-pocket limit of $9,850.
That doesn’t mean a member will spend $9,850.
The maximum out-of-pocket limit is a ceiling on applicable cost-sharing, not an estimate of what you will spend.
But it is an important measure of your potential financial exposure if you have significant healthcare needs.
What Should You Do If Your Medicare Advantage Plan Is Ending?
First:
Don’t ignore the notice from your insurance company.
If your plan is being discontinued, read the notice carefully.
It should explain what is happening to your coverage and what options are available to you.
Then consider your alternatives.
Depending on your circumstances and what’s available where you live, those alternatives may include:
- Enrolling in another Medicare Advantage plan
- Returning to Original Medicare
- Adding a standalone Medicare Part D prescription drug plan to Original Medicare
- Considering Medicare Supplement insurance if you’re eligible and the coverage fits your needs
- In some Minnesota counties, considering a Medicare Cost Plan
Don’t assume that the replacement plan offered by your current insurance company is automatically the best option for you.
And don’t assume that staying with the same insurance company means keeping the same coverage.
Compare the actual 2027 plans.
Check Your Doctors and Hospitals
If you’re considering another Medicare Advantage plan, check the provider network.
Don’t simply ask:
“Does my doctor take Medicare?”
Instead ask:
“Is my doctor in-network for this specific Medicare Advantage plan for 2027?”
Check:
- Your primary care doctor
- Specialists
- Preferred clinic
- Preferred hospital
- Healthcare system
- Other providers you regularly use
A replacement Medicare Advantage plan may have different costs, benefits or network arrangements from your current plan.
Check Every Prescription You Take
Prescription drug coverage should also be reviewed carefully.
For each medication, check:
- Is it covered by the plan?
- What formulary tier is it on?
- What will it cost?
- Does a deductible apply?
- Is prior authorization required?
- Does step therapy apply?
- Are there quantity limits?
- Which pharmacies provide the most favorable cost-sharing?
Don’t assume that because your prescriptions were covered well in 2026, they’ll work the same way under a different 2027 plan.
What About Original Medicare?
Someone losing a Medicare Advantage plan may also consider returning to Original Medicare.
Original Medicare works differently from Medicare Advantage.
With Original Medicare, you generally can use any doctor or hospital in the United States that participates in Medicare and is accepting Medicare patients.
Original Medicare itself does not have an annual maximum out-of-pocket limit for covered Medicare Part A and Part B services.
Some beneficiaries therefore combine Original Medicare with Medicare Supplement insurance to help pay certain costs that Original Medicare doesn’t cover.
Prescription drug coverage is generally obtained separately through a Medicare Part D prescription drug plan.
Minnesota has its own Medicare Supplement rules, so don’t rely solely on general information written for beneficiaries in other states when evaluating Medicare Supplement coverage here.
If Your Plan Is Ending, Ask About Your Medicare Supplement Rights
This is particularly important.
Losing Medicare Advantage coverage because a plan is leaving Medicare or no longer serving your area can create Medicare Supplement rights that may not exist when someone voluntarily leaves a Medicare Advantage plan.
These protections are commonly referred to as guaranteed-issue rights.
If your Medicare Advantage plan is ending, keep every notice you receive from the plan.
Those documents may be important if you decide to investigate Medicare Supplement coverage.
Because Medicare Supplement rules and eligibility can depend on the specific circumstances, verify your individual rights before making a coverage change.
Don’t Forget Prescription Drug Coverage
If you’re moving from a Medicare Advantage plan that includes prescription drug coverage to Original Medicare, prescription coverage deserves immediate attention.
Original Medicare generally doesn’t provide the outpatient prescription drug coverage that was included in your Medicare Advantage plan.
You may need to enroll in a standalone Medicare Part D prescription drug plan.
For 2027, the Centers for Medicare & Medicaid Services reports that Minnesota will have nine standalone Medicare Part D prescription drug plans, compared with 11 in 2026.
Review your actual medications when comparing those plans.
Important Dates for 2027 Coverage
Medicare’s Annual Enrollment Period runs:
October 15 through December 7, 2026.
During this period, Medicare beneficiaries can make certain changes to their Medicare Advantage and prescription drug coverage for 2027.
Changes made during the Annual Enrollment Period generally take effect:
January 1, 2027.
People whose Medicare Advantage plans are not renewing may also have additional enrollment rights beyond the Annual Enrollment Period.
Read the notice from your current plan carefully so you understand the deadlines and options that apply specifically to you.
Don’t Wait Until December 7
With more than 320,000 Minnesotans affected by discontinued plans, this is likely to be an unusually busy Medicare enrollment season in Minnesota.
If your plan is ending, start reviewing your options as soon as 2027 plan information becomes available.
Gather:
Your Medicare card
Your plan termination or Annual Notice of Change letter
Your prescription list, including dosage and frequency
Your doctors and specialists
Your preferred hospitals and healthcare systems
Then compare your available 2027 options.
Even If Your Plan Isn’t Ending, Review It
The 320,000-plus Minnesotans losing plans aren’t the only people who should pay attention this year.
If your Medicare Advantage plan is continuing into 2027, review:
- Premium
- Deductibles
- Copays
- Coinsurance
- Maximum out-of-pocket limit
- Prescription coverage
- Provider network
- Supplemental benefits
Your plan doesn’t have to disappear for your coverage to change significantly.
The Bottom Line
The Minnesota Medicare Advantage market is changing substantially for 2027.
More than 320,000 Minnesotans are enrolled in plans that are being discontinued, according to the Minnesota Star Tribune.
Blue Cross and Blue Shield of Minnesota, Medica, HealthPartners, UnitedHealthcare and Humana are all making significant changes.
But the most important question isn’t:
“Which insurance companies are changing?”
It’s:
“What does this mean for my coverage?”
If your plan is ending, don’t panic — but don’t ignore it either.
Read your notice.
Review your options.
Check your doctors.
Check your prescriptions.
Compare your total potential costs.
And understand your rights before making a decision.
For many Minnesotans, 2027 will require a more careful Medicare review than usual.
Learn First. Decide With Confidence.
Medicare Guidance for Minnesotans
At YourMedicareMN, our focus is education first.
We help Minnesota Medicare beneficiaries understand changes to Medicare coverage, compare their options and make informed decisions based on their individual healthcare needs.
Visit Contact Us to schedule a personalized Medicare review and get answers tailored to your situation.
For official Medicare information, visit the Medicare.gov website.
YourMedicareMN is not connected with or endorsed by the U.S. government or the federal Medicare program. Plan availability and benefits vary by location and plan. Contact the plan or Medicare for complete plan information.
Learn First. Decide With Confidence.
YourMedicareMN
Medicare Guidance for Minnesotans