If you’re happy with your Medicare coverage, do you need to change plans?
No.
Changing Medicare plans simply because another Annual Enrollment Period has arrived isn’t the goal.
But Medicare Advantage and Medicare prescription drug plans can change from year to year. Your healthcare needs can change too.
That’s why it’s worth reviewing your coverage each fall.
Sometimes that review confirms that your current plan continues to fit your needs.
Other times, it identifies a reason to consider your alternatives.
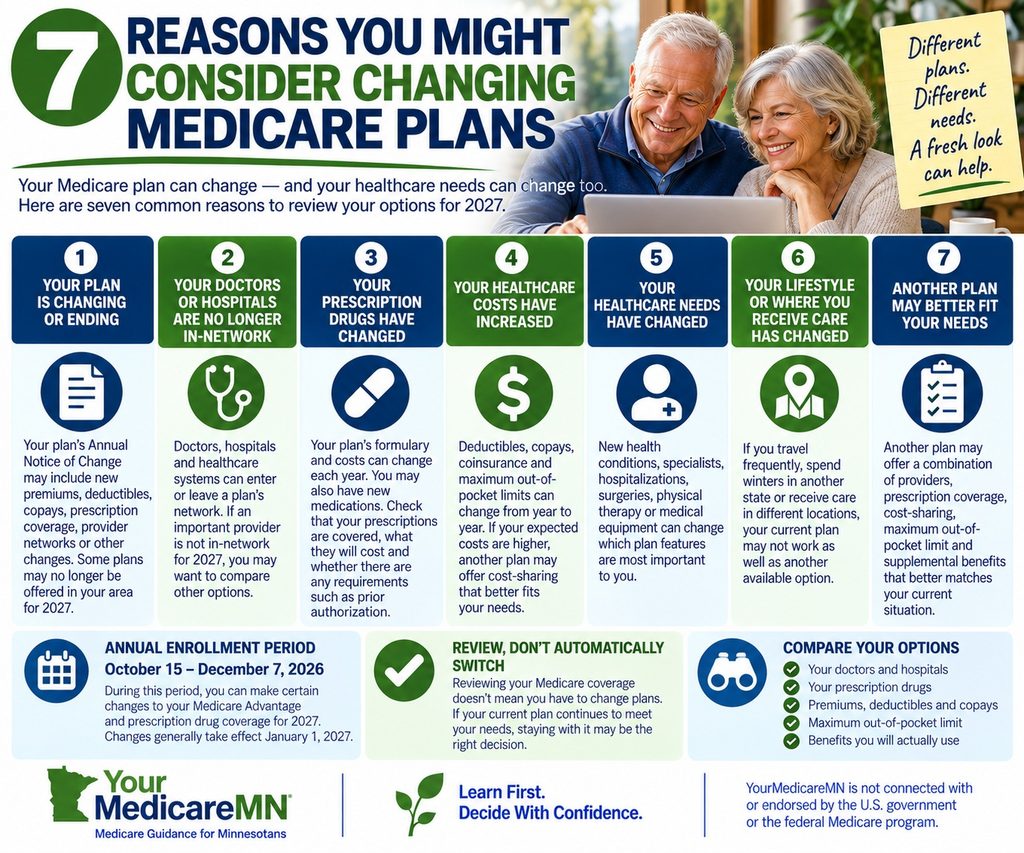
Here are seven reasons you might consider changing Medicare plans.
1. Your Current Plan Is Changing — or Ending
If you’re enrolled in a Medicare Advantage or Medicare prescription drug plan, your plan sends you an Annual Notice of Change each fall.
Read it carefully.
It explains important changes that will take effect January 1.
Your plan could change:
- Monthly premiums
- Deductibles
- Copays
- Coinsurance
- Maximum out-of-pocket limits
- Prescription drug coverage
- Provider networks
- Supplemental benefits
- Other coverage rules
Sometimes a plan may stop being offered in your area entirely.
A plan that worked well for you this year may still work well next year — but don’t assume that nothing has changed.
Particularly important for Minnesota in 2027
This deserves additional attention this year.
Minnesota is experiencing significant Medicare Advantage plan changes for 2027, with several major insurance companies discontinuing or restructuring plans.
If your plan is ending, carefully read the notice you receive from the plan. Your situation may also provide enrollment rights beyond the regular Annual Enrollment Period.
Keep the notices your plan sends you.
They may contain important information about your coverage options and enrollment rights.
2. Your Doctors or Hospitals Are No Longer in the Network
If you have Medicare Advantage, your provider network can be an important reason to review your coverage.
Perhaps your plan hasn’t changed much — but your doctor has.
Doctors, hospitals and healthcare systems can enter or leave Medicare Advantage networks.
If an important provider is no longer in-network, consider how that affects your coverage.
Check:
- Your primary care doctor
- Specialists
- Preferred clinic
- Preferred hospital
- Healthcare system
- Other providers you regularly use
Don’t simply ask:
“Does my doctor take Medicare?”
A doctor may accept Original Medicare without participating in your particular Medicare Advantage plan.
Instead ask:
“Is this provider in-network for this specific Medicare Advantage plan for 2027?”
If a doctor or hospital you rely on isn’t in-network, that’s a reason to investigate your alternatives.
It doesn’t automatically mean you should change plans.
Your options and costs depend on your plan type and its rules for out-of-network care.
3. Your Prescription Drugs Have Changed
Your prescriptions can change in two ways.
Your plan’s drug coverage can change.
And:
The medications you take can change.
Either one can be a good reason to review your Medicare coverage.
For each prescription, check:
- Is the medication covered?
- What formulary tier is it on?
- What will it cost?
- Does a deductible apply?
- Is prior authorization required?
- Does step therapy apply?
- Are there quantity limits?
- Which pharmacies offer the most favorable cost-sharing?
Don’t assume that because your prescription was covered well this year, it will work exactly the same way next year.
Likewise, if you’ve started taking an expensive medication during the year, the plan you originally selected may no longer be the best match for your prescription needs.
When comparing plans, use your actual medications, dosages and preferred pharmacies.
4. Your Healthcare Costs Have Increased
A low monthly premium doesn’t necessarily mean low total healthcare costs.
Your Medicare Advantage plan might still have a $0 monthly plan premium while other costs have increased.
Review:
- Deductibles
- Primary care copays
- Specialist copays
- Hospital costs
- Outpatient procedure costs
- Coinsurance
- Prescription costs
- Maximum out-of-pocket limit
Medicare Advantage plans have an annual maximum out-of-pocket limit for covered Medicare Part A and Part B services, but that limit varies by plan.
If your plan’s cost-sharing has increased significantly, another plan may deserve consideration.
But compare the entire plan.
A plan with a lower specialist copay, for example, isn’t necessarily less expensive overall if it has higher hospital costs, a less suitable prescription formulary or a provider network that doesn’t include your doctors.
Ask:
“What could this plan actually cost me based on the healthcare I use?”
That’s more useful than comparing premiums alone.
5. Your Healthcare Needs Have Changed
Sometimes the Medicare plan hasn’t changed much.
You have.
Think about what’s happened during the past year.
Have you:
- Started seeing a new specialist?
- Been diagnosed with a condition requiring ongoing treatment?
- Had surgery?
- Experienced a hospitalization?
- Started physical therapy?
- Begun using durable medical equipment?
- Started taking new prescriptions?
- Changed doctors or healthcare systems?
Changes like these can alter which plan features matter most to you.
Perhaps specialist copays weren’t particularly important when you selected your plan because you rarely saw a specialist.
Now you see three specialists regularly.
Perhaps hospital costs weren’t something you paid much attention to before a recent hospitalization.
Or perhaps you now use medical equipment that involves coinsurance.
Your Medicare coverage should be evaluated based on your current healthcare needs, not simply the needs you had when you originally enrolled.
6. Your Lifestyle or Where You Receive Healthcare Has Changed
Where you receive healthcare can matter, particularly with Medicare Advantage.
Have you started:
- Traveling more frequently?
- Spending winters in another state?
- Staying with family for extended periods?
- Receiving care from specialists farther from home?
- Spending significant time outside your plan’s local service area?
Medicare Advantage plans may use provider networks and service areas.
Emergency and urgently needed services have protections when you’re away from your plan’s network.
Routine healthcare is different.
Coverage for routine out-of-network services depends on the particular Medicare Advantage plan and plan type.
For example, Health Maintenance Organization and Preferred Provider Organization plans generally have different rules regarding non-emergency out-of-network care.
If you’re a Minnesota resident who now spends several months each winter somewhere else, review how your current coverage works when you’re away.
A plan that worked well when you rarely traveled may not fit your new lifestyle as well.
7. Another Plan Better Fits Your Current Needs
Sometimes your current Medicare plan isn’t doing anything particularly wrong.
You simply discover that another available option appears to fit your current situation better.
Perhaps another plan:
- Includes your doctors and hospitals
- Covers your prescriptions differently
- Has cost-sharing that better matches the services you use
- Has a lower maximum out-of-pocket limit
- Has a pharmacy network that works better for you
- Provides supplemental benefits you would actually use
- Works better with your travel patterns
This doesn’t mean you should switch simply because another plan has one attractive feature.
Compare the whole plan.
A lower premium may come with higher cost-sharing.
A lower maximum out-of-pocket limit may come with a provider network that doesn’t include an important doctor.
Better dental benefits may not compensate for less favorable prescription coverage.
There isn’t one Medicare plan that’s best for everyone.
The question is whether another available option better fits your individual healthcare and financial needs.
Reasons NOT to Change Medicare Plans
It’s equally important to understand when changing plans may not make sense.
Don’t change simply because:
A television advertisement makes another plan sound better.
Advertising may emphasize selected benefits without showing you how the entire plan fits your situation.
A friend loves their Medicare plan.
Your friend may have different doctors, prescriptions and healthcare needs.
Another plan has a $0 premium.
A $0 Medicare Advantage plan premium doesn’t mean $0 healthcare costs.
Another plan offers an attractive extra benefit.
Dental, vision, hearing and other supplemental benefits can be useful, but they should be considered alongside medical coverage, provider networks, prescriptions and costs.
You think you’re supposed to change plans every year.
You’re not.
If your existing coverage continues to meet your needs, remaining in your current plan may be entirely appropriate.
What Should You Compare Before Changing?
Before making a Medicare plan change, compare your current coverage with the alternative you’re considering.
Look at:
Doctors and hospitals
Are the providers you want to use available under the plan?
Prescriptions
Are your medications covered, and what will they cost?
Premiums
What will you pay each month?
Deductibles
What must you pay before certain coverage begins paying?
Copays and coinsurance
What will you pay when you actually receive healthcare?
Maximum out-of-pocket limit
What is your potential annual exposure for covered Medicare Part A and Part B services under a Medicare Advantage plan?
Travel
How does the plan work when you’re away from home?
Supplemental benefits
Which additional benefits would you actually use, and what are their limitations?
Don’t Cancel Your Current Coverage Before Understanding the Consequences
This is especially important if you’re considering moving between different types of Medicare coverage.
Switching from one Medicare Advantage plan to another is different from leaving Medicare Advantage and returning to Original Medicare.
And returning to Original Medicare doesn’t necessarily mean you can purchase any Medicare Supplement policy you want without medical underwriting.
Medicare Supplement rights depend on your circumstances and applicable federal and Minnesota rules.
If you’re considering leaving Medicare Advantage for Original Medicare with Medicare Supplement insurance, verify your Medicare Supplement eligibility and rights before assuming coverage will be available on the terms you expect.
Minnesota has Medicare Supplement rules that differ in important ways from the standardized structure used in many other states.
When Can You Change Medicare Plans?
For 2027 coverage, Medicare’s Annual Enrollment Period runs:
October 15 through December 7, 2026.
During this period, people with Medicare can make certain changes involving Medicare Advantage and Medicare prescription drug coverage.
Changes made during the Annual Enrollment Period generally take effect:
January 1, 2027.
Depending on your circumstances, you may also qualify for a Special Enrollment Period at another time.
People already enrolled in Medicare Advantage also have a separate Medicare Advantage Open Enrollment Period from January 1 through March 31, during which certain changes can be made.
Different enrollment periods have different rules.
Use Medicare’s Official Plan Comparison Tool
Medicare Plan Finder at Medicare.gov allows you to compare Medicare Advantage and Medicare prescription drug plans available where you live.
Compare 2027 plans with Medicare Plan Finder
For a meaningful comparison, enter your actual:
- Prescription medications
- Dosages
- Pharmacies
Then examine more than the premium.
Review estimated costs, provider information, prescription coverage and plan details.
Plan availability varies by location, so compare the plans actually available where you live.
The Best Outcome May Be Keeping the Plan You Already Have
After reading seven reasons you might consider changing Medicare plans, here’s an equally important point:
You may review everything and decide not to change anything.
That’s a perfectly reasonable result.
If you’ve checked your:
- Plan changes
- Doctors
- Hospitals
- Prescriptions
- Costs
- Network
- Benefits
- Healthcare needs
and your current plan continues to work well for you, you may decide to keep it.
The purpose of an annual Medicare review isn’t to find a reason to change.
It’s to make sure you understand the coverage you’ll have for the coming year.
The Bottom Line
You might consider changing Medicare plans if:
1. Your current plan is changing or ending.
2. Your doctors or hospitals are no longer in-network.
3. Your prescription needs or drug coverage have changed.
4. Your healthcare costs have increased.
5. Your healthcare needs have changed.
6. Your lifestyle or where you receive healthcare has changed.
7. Another available plan better fits your current needs.
None of these automatically means you should change plans.
They’re reasons to take another look.
Compare your options carefully, consider the entire plan and make your decision based on your individual healthcare needs.
Sometimes changing plans will make sense.
Sometimes staying exactly where you are will make sense.
Either way, the important thing is that the decision is informed.
Medicare Guidance for Minnesotans
At YourMedicareMN, our focus is education first.
We help Minnesota Medicare beneficiaries understand changes to Medicare coverage, compare their options and make informed decisions based on their individual healthcare needs.
Visit Contact Us to schedule a personalized Medicare review and get answers tailored to your situation.
For official Medicare information, visit the Medicare.gov website.
YourMedicareMN is not connected with or endorsed by the U.S. government or the federal Medicare program. Plan availability and benefits vary by location and plan. Contact the plan or Medicare for complete plan information.
Learn First. Decide With Confidence.
YourMedicareMN
Medicare Guidance for Minnesotans