Every fall, people with Medicare have an opportunity to take a fresh look at their coverage for the coming year.
Even if you’re happy with your current Medicare plan, an annual review is worthwhile.
Why?
Because your plan can change — and your healthcare needs can change too.
Premiums, deductibles, copays, prescription drug coverage, provider networks and other benefits may be different in 2027. You may also have new prescriptions, new doctors or different healthcare priorities than you had a year ago.
That doesn’t mean you need to change plans.
It means you should understand what you’re keeping.
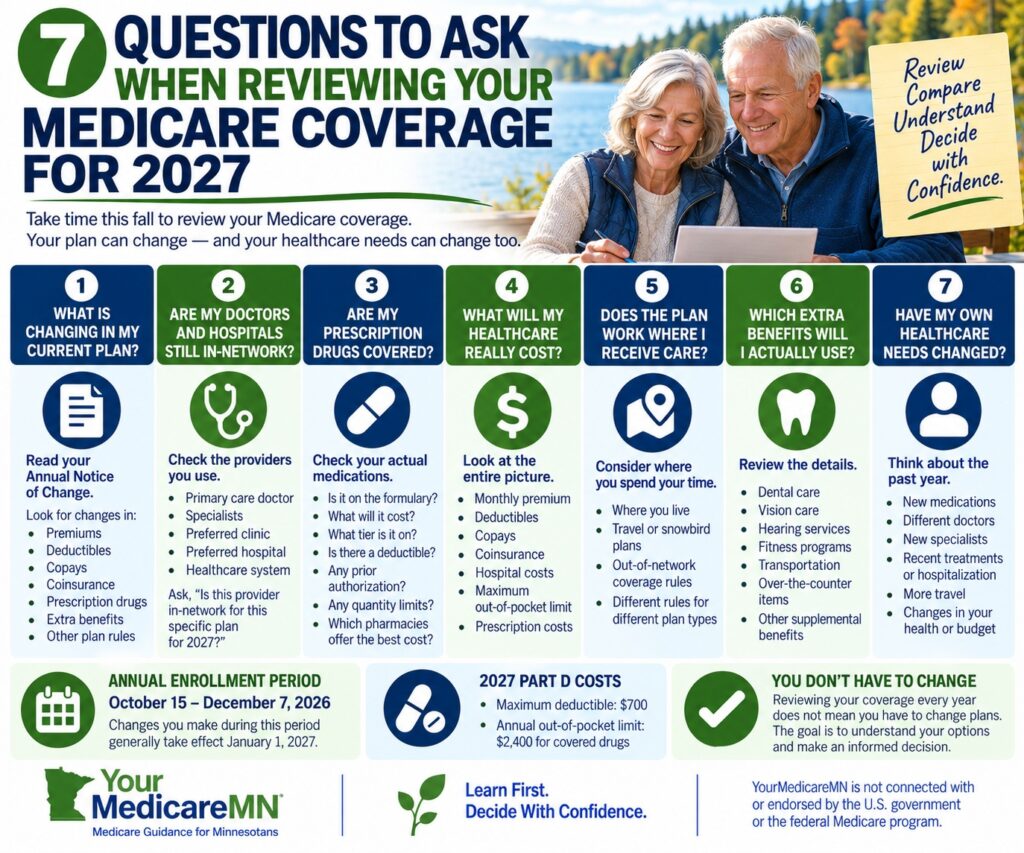
Here are seven questions to ask when reviewing your Medicare coverage for 2027.
1. What Is Changing in My Current Medicare Plan for 2027?
Start with the plan you already have.
If you’re enrolled in a Medicare Advantage or Medicare prescription drug plan, your plan sends you an Annual Notice of Change each fall.
Don’t throw it away.
The Annual Notice of Change explains important changes to your coverage that take effect in January.
Look for changes involving:
- Monthly premiums
- Deductibles
- Copays
- Coinsurance
- Maximum out-of-pocket limits
- Prescription drug coverage
- Supplemental benefits
- Other plan rules or coverage
If your plan worked well in 2026, that’s useful information.
But you’re choosing coverage for 2027.
Review the new year’s benefits and costs rather than assuming they’ll be identical to this year’s.
2. Are My Doctors and Hospitals Still in the Network?
If you have a Medicare Advantage plan, provider networks can be an important part of your annual review.
Check the providers you actually use, including:
- Primary care doctor
- Specialists
- Preferred clinic
- Preferred hospital
- Healthcare system
- Other providers important to your care
Don’t simply ask:
“Does my doctor take Medicare?”
A provider may accept Original Medicare without participating in your particular Medicare Advantage plan.
Instead ask:
“Is this provider in-network for this specific Medicare Advantage plan for 2027?”
Check the exact plan — not just the insurance company.
For providers that are particularly important to you, consider checking the plan’s provider directory and confirming the information with the plan and provider’s office.
3. Are My Prescription Drugs Covered in 2027 — and What Will They Cost?
If you take prescription medications, this should be one of the most important parts of your annual Medicare review.
Don’t simply ask whether your plan includes prescription drug coverage.
Check your actual medications.
For each prescription, consider:
- Is the medication on the plan’s formulary?
- What tier is it on?
- What will I pay?
- Does a deductible apply?
- Are there prior authorization requirements?
- Does step therapy apply?
- Are there quantity limits?
- Which pharmacies offer the most favorable cost-sharing under the plan?
Drug formularies and costs can change from year to year.
Your medications can change too.
For 2027, Medicare Part D continues to provide an annual limit on out-of-pocket spending for covered Part D drugs. The 2027 out-of-pocket threshold is $2,400, up from $2,100 in 2026.
The maximum deductible under the defined standard Part D benefit is $700 for 2027. Individual plans may have a lower deductible or structure their coverage differently within Medicare’s rules.
These are important protections and costs to understand, but your individual prescription expenses will still depend on the medications you take and the plan you choose.
4. What Will My Healthcare Really Cost?
A monthly premium is only one part of your Medicare costs.
When comparing coverage, consider the entire financial picture.
Look at:
Premiums
What will you pay each month?
Deductibles
What might you need to pay before certain coverage begins paying?
Copays
What fixed amounts will you pay for services such as doctor or specialist visits?
Coinsurance
What percentage might you pay for certain services?
Hospital costs
How does the plan handle inpatient and outpatient care?
Maximum out-of-pocket limit
If you have Medicare Advantage, what is the applicable annual limit on your cost-sharing for covered Medicare Part A and Part B services?
Don’t evaluate a plan based solely on its premium.
A $0-premium Medicare Advantage plan means the plan charges $0 for its monthly plan premium. It doesn’t mean you’ll have no healthcare expenses.
Ask yourself two questions:
What am I likely to spend in a normal year?
And:
What could I potentially spend if I have a year with significant healthcare needs?
Both matter.
5. Does the Plan Work Where I Receive Healthcare?
Where you receive healthcare matters — especially if you have Medicare Advantage.
Consider not only where you live, but where you actually spend your time.
Do you:
- Travel frequently?
- Spend winters in another state?
- Visit family for extended periods?
- Receive care from a healthcare system outside your immediate area?
- Regularly see specialists in another city?
Emergency and urgently needed care have protections when you’re away from your Medicare Advantage plan’s network.
Routine care is different.
Coverage for routine out-of-network care depends on your particular Medicare Advantage plan and plan type.
For example, Health Maintenance Organization and Preferred Provider Organization plans generally have different rules for non-emergency out-of-network care.
If you’re a Minnesota snowbird or frequent traveler, don’t wait until you’re in another state to find out how your plan works there.
Check before you enroll.
6. Which Extra Benefits Will I Actually Use?
Medicare Advantage plans may offer supplemental benefits beyond Original Medicare.
Depending on the plan, these might include benefits involving:
- Dental care
- Vision care
- Hearing services
- Fitness programs
- Transportation
- Over-the-counter items
- Other supplemental benefits
These benefits can be valuable.
But don’t evaluate a Medicare Advantage plan based on the number of extra benefits advertised.
Instead ask:
Which benefits will I actually use?
Then look at the details.
For example, if dental coverage matters to you, find out:
- Which dental services are covered?
- Is there an annual benefit limit?
- Is there a provider network?
- What cost-sharing applies?
- Are there other coverage restrictions?
The same principle applies to vision, hearing and other supplemental benefits.
An attractive extra benefit doesn’t necessarily compensate for a provider network, prescription formulary or cost structure that doesn’t fit your healthcare needs.
7. Have My Own Healthcare Needs Changed?
This may be the most overlooked question in an annual Medicare review.
Your Medicare plan isn’t the only thing that can change.
You can change too.
Think about what’s happened during the past year.
Have you:
- Started taking a new medication?
- Stopped taking a medication?
- Started seeing a specialist?
- Changed doctors?
- Had surgery or a hospitalization?
- Developed an ongoing need for physical therapy or other treatment?
- Begun traveling more?
- Started spending part of the year in another state?
- Changed your financial priorities?
A Medicare plan that fit your needs a year ago may still be an excellent fit.
Or your circumstances may now make another option worth considering.
Your annual Medicare review should evaluate both sides of the equation:
What changed with my coverage?
and
What changed with me?
Do You Need to Change Medicare Plans Every Year?
No.
This is worth emphasizing.
Reviewing your Medicare coverage every year does not mean changing your Medicare coverage every year.
If you’ve reviewed your doctors, hospitals, prescriptions, costs and benefits and your current coverage continues to meet your needs, staying with it may be entirely appropriate.
The goal of an annual Medicare review isn’t to find a reason to switch.
The goal is to make an informed decision.
Sometimes that decision is to change.
Sometimes it’s to stay exactly where you are.
When Can You Make Changes for 2027?
Medicare’s Annual Enrollment Period runs from:
October 15 through December 7, 2026.
During this period, people with Medicare can make certain changes to Medicare Advantage and Medicare prescription drug coverage for 2027.
Coverage changes made during the Annual Enrollment Period generally take effect January 1, 2027.
You can use Medicare Plan Finder at Medicare.gov to compare the 2027 Medicare Advantage and prescription drug plans available where you live.
Remember that Medicare plan availability is local.
The plans available in one Minnesota county may be different from those available in another.
Your 2027 Medicare Review Checklist
Before deciding on your Medicare coverage for 2027, make sure you can answer these seven questions:
1. What is changing in my current plan?
2. Are my doctors and hospitals still in-network?
3. Are my prescriptions covered, and what will they cost?
4. What will my healthcare really cost?
5. Does the plan work where I receive healthcare?
6. Which extra benefits will I actually use?
7. Have my healthcare needs changed?
If you can answer those questions, you’ll have a much clearer picture of whether your current coverage continues to fit your needs.
The Bottom Line
Choosing Medicare coverage isn’t simply about finding the lowest premium or the plan with the longest list of extra benefits.
It’s about finding coverage that works with:
Your doctors.
Your prescriptions.
Your healthcare needs.
Your budget.
And where you receive care.
Take the time to review those things before making your 2027 Medicare decision.
You may discover that another plan deserves consideration.
Or you may confirm that the coverage you already have continues to work well for you.
Either outcome can be a good result.
Because the purpose of reviewing your Medicare coverage isn’t to change plans.
It’s to understand your choices and make an informed decision.
Medicare Guidance for Minnesotans
At YourMedicareMN, our focus is education first.
We help Minnesota Medicare beneficiaries understand their Medicare options, review changes and make informed decisions based on their individual healthcare needs.
Visit Contact Us to schedule a personalized Medicare review and get answers tailored to your situation.
For official Medicare information, visit the Medicare.gov website.
YourMedicareMN is not connected with or endorsed by the U.S. government or the federal Medicare program. Plan availability and benefits vary by location and plan. Contact the plan or Medicare for complete plan information.
Learn First. Decide With Confidence.
YourMedicareMN
Medicare Guidance for Minnesotans