A $0 monthly premium doesn’t necessarily mean $0 healthcare costs.
The Medicare Annual Enrollment Period is officially underway. From October 15 through December 7, 2026, Medicare beneficiaries have an opportunity to review their coverage and make changes for 2027.
With television advertisements, mailers, and online promotions highlighting Medicare plans with $0 monthly premiums, it’s easy to focus on one number: the monthly cost.
But choosing Medicare coverage based on the premium alone could leave you paying more throughout the year.
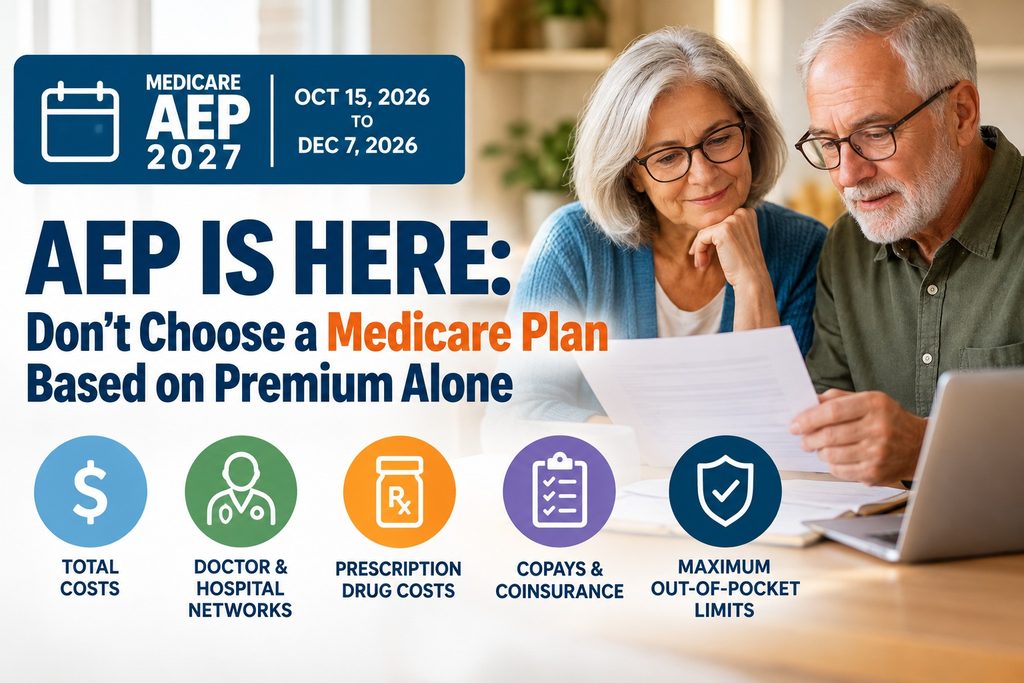
At YourMedicareMN, we encourage beneficiaries to look beyond the advertised premium and consider the total cost of their healthcare coverage.
1. A $0 Premium Doesn’t Mean Free Healthcare
Many Medicare Advantage plans offer a $0 monthly plan premium. That can be attractive, particularly for retirees managing a fixed income.
However, even with a $0 plan premium, you may still have expenses such as:
- Medicare Part B premiums
- Copayments for doctor and specialist visits
- Coinsurance for certain medical services
- Hospital inpatient costs
- Prescription drug costs
- Deductibles and other out-of-pocket expenses
Important: You generally must continue paying your Medicare Part B premium even when enrolled in a $0-premium Medicare Advantage plan, unless another program or plan benefit pays some or all of it.
The real question isn’t simply, “What’s my monthly premium?”
It’s “What might my healthcare cost over the entire year?”
2. Understand Your Maximum Out-of-Pocket Limit
Medicare Advantage plans have an annual maximum out-of-pocket limit for covered Part A and Part B services.
This limit helps protect beneficiaries from unlimited cost-sharing for covered medical services.
However, there are important details:
- The limit varies by plan.
- Plans with out-of-network coverage may have separate in-network and combined limits.
- Prescription drug costs generally do not count toward the medical maximum out-of-pocket limit.
- Monthly premiums do not count toward this limit.
Consider two hypothetical Medicare Advantage plans:
| Feature | Plan A | Plan B |
|---|---|---|
| Monthly plan premium | $0 | $45 |
| Annual plan premiums | $0 | $540 |
| In-network medical maximum out-of-pocket | $6,700 | $3,900 |
Plan A has the lower premium, but Plan B provides a lower ceiling on covered in-network medical cost-sharing.
That doesn’t automatically make Plan B better. It demonstrates why comparing premiums alone can be misleading.
3. Check Your Doctors and Hospitals
Provider networks can significantly affect both healthcare costs and access to care.
Before selecting a Medicare Advantage plan, determine whether your preferred providers participate in that specific plan’s network.
For Minnesota beneficiaries, this is especially important in communities such as Ely, Virginia, Hibbing, Duluth, and other parts of northern Minnesota, where provider choices may be more limited.
Ask these questions:
- Is my primary care provider in the plan’s network?
- Are my specialists included?
- Does my preferred hospital participate?
- Will I need referrals for specialist care?
- What happens if I receive non-emergency care outside the network?
A plan with a lower premium may not be the most economical choice if your preferred providers are out of network.
Remember: An insurance company may offer several Medicare plans with different networks. Acceptance of one plan does not mean a provider accepts every plan offered by that company.
Always verify participation in the exact plan for 2027.
4. Don’t Overlook Prescription Drug Costs
Prescription drug coverage can be one of the most significant differences between Medicare plans.
Two plans may have similar monthly premiums but very different prescription drug expenses.
When comparing coverage, consider:
- Whether your medications are covered
- Which formulary tiers your medications fall into
- Applicable deductibles
- Copayments and coinsurance
- Pharmacy network participation
- Prior authorization, quantity limits, and step therapy requirements
For 2027, the annual out-of-pocket cap for covered Part D prescription drugs is $2,400.
That protection is important, but it doesn’t mean every beneficiary will spend $2,400. Actual expenses depend on the medications used, the plan’s coverage, and applicable cost-sharing.
Reviewing your specific prescriptions and preferred pharmacy is essential.
5. Compare Copayments and Coinsurance
Two Medicare Advantage plans with the same premium can have very different cost-sharing structures.
One plan may charge less for primary care visits but more for specialists or hospitalization.
Another may offer lower specialist copayments but higher costs for certain outpatient procedures.
Pay particular attention to:
- Primary care and specialist visits
- Outpatient surgery
- Diagnostic imaging
- Emergency room visits
- Hospital admissions
- Skilled nursing facility care
- Physical and occupational therapy
Think about the healthcare services you’re likely to use in 2027.
A plan that works well for someone who rarely visits a doctor may not be the best choice for someone managing several chronic conditions.
6. Consider Your Total Annual Healthcare Costs
Rather than comparing only monthly premiums, estimate what each plan might cost over an entire year.
A useful starting point is:
Annual plan premiums + expected medical cost-sharing + expected prescription drug costs = estimated annual plan-related healthcare costs
Remember to account for the Medicare Part B premium and any other applicable coverage costs when comparing different coverage strategies.
This estimate isn’t a guarantee. Unexpected medical needs can change your expenses substantially.
That’s why it’s helpful to compare both your expected annual costs and your potential financial exposure if you need extensive medical care.
7. Remember That Minnesota Has Different Coverage Options
Minnesota Medicare beneficiaries may have several coverage strategies available, depending on their county and eligibility.
These can include:
- Original Medicare with a Medicare Supplement insurance policy
- Medicare Advantage plans
- Medicare Cost plans in counties where offered
- Stand-alone Medicare Prescription Drug Plans
These options work differently.
For example, Medicare Supplement insurance generally helps pay certain out-of-pocket costs under Original Medicare, while Medicare Advantage plans provide Medicare-covered services through a private insurance plan.
Medicare Cost plans have different rules regarding how Original Medicare and the Cost plan coordinate coverage.
Don’t assume the coverage option with the lowest monthly premium provides the lowest overall cost or the best access to care.
Also remember that switching from Medicare Advantage to Medicare Supplement insurance may involve eligibility and enrollment considerations. Minnesota has certain protections, but not every beneficiary has an unrestricted right to purchase every Supplement policy at any time.
8. Review Your Coverage Even If You’re Happy With Your Current Plan
If your existing Medicare coverage has worked well, you may be inclined to keep it.
That may be the right decision.
However, Medicare plans can change from year to year.
For 2027, review your plan’s Annual Notice of Change and look for changes involving:
- Monthly premiums
- Deductibles and copayments
- Provider networks
- Prescription drug formularies
- Pharmacy networks
- Additional benefits
- Maximum out-of-pocket limits
A plan that worked well in 2026 may not provide the same value in 2027.
You don’t necessarily need to change plans. You do need to understand what you’re keeping.
Important Medicare Enrollment Dates
The Medicare Annual Enrollment Period runs from October 15 through December 7, 2026.
During this period, eligible beneficiaries can generally:
- Switch from Original Medicare to a Medicare Advantage plan.
- Switch from Medicare Advantage back to Original Medicare.
- Change from one Medicare Advantage plan to another.
- Join, switch, or drop Medicare prescription drug coverage.
Changes made during this period generally take effect January 1, 2027.
Be aware that leaving Medicare Advantage for Original Medicare does not automatically guarantee your ability to purchase a Medicare Supplement policy.
The Bottom Line: Look Beyond the Premium
When evaluating Medicare coverage for 2027, remember that the lowest monthly premium doesn’t always mean the lowest total cost.
The right coverage decision depends on your healthcare needs, medications, preferred doctors and hospitals, financial priorities, and available plans.
Before enrolling, compare:
- Total expected annual costs
- Maximum out-of-pocket exposure
- Provider and hospital networks
- Prescription drug coverage
- Copayments and coinsurance
- Coverage restrictions and additional benefits
A good Medicare decision isn’t about finding the lowest advertised premium. It’s about finding coverage that fits your needs and budget.
Medicare Guidance for Minnesotans
At YourMedicareMN, our focus is education first.
We help Minnesota Medicare beneficiaries understand changes to Medicare coverage, compare their options and make informed decisions based on their individual healthcare needs.
Visit Contact Us to schedule a personalized Medicare review and get answers tailored to your situation.
For official Medicare information, visit the Medicare.gov website.
YourMedicareMN is not connected with or endorsed by the U.S. government or the federal Medicare program. Plan availability and benefits vary by location and plan. Contact the plan or Medicare for complete plan information.
Learn First. Decide With Confidence.
YourMedicareMN
Medicare Guidance for Minnesotans