Comparing Medicare plans can feel overwhelming. Between monthly premiums, deductibles, provider networks, prescription drug coverage, and extra benefits, there is a lot to consider.
The good news? You do not need to understand every Medicare plan available to you. You only need to identify the plans that best meet your healthcare needs and financial priorities.
Whether you are new to Medicare or reviewing your coverage for 2027, this simple approach can help you make an informed decision without getting lost in the details.
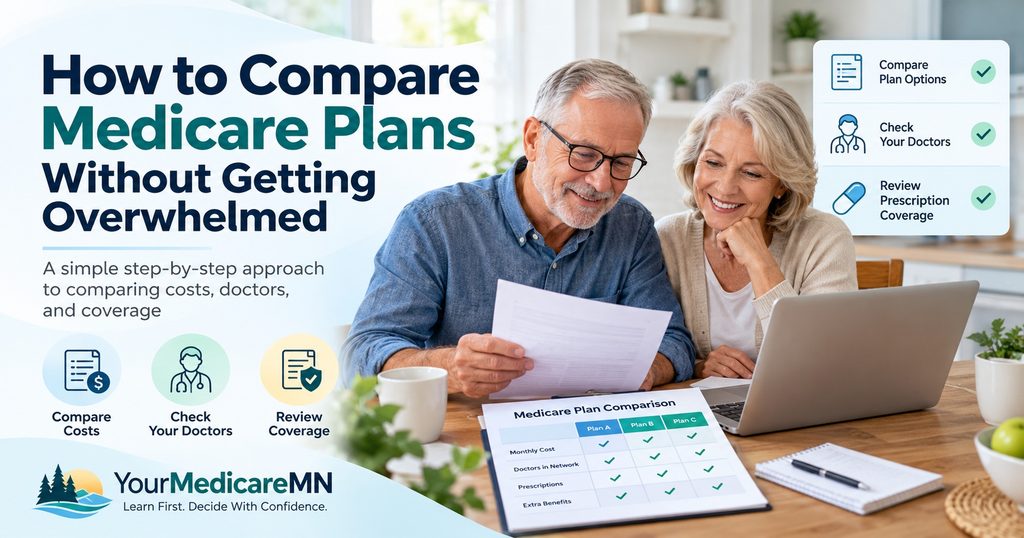
Step 1: Start With Your Healthcare Needs — Not the Plans
One of the biggest mistakes people make is looking at plan advertisements before deciding what matters most to them.
Instead, begin by answering a few questions:
- Which doctors, specialists, and hospitals do I want to continue using?
- What prescription medications do I take?
- How frequently do I visit doctors or receive medical treatment?
- Do I travel frequently or spend part of the year in another state?
- Would I prefer lower monthly premiums or more predictable healthcare expenses?
- How important are dental, vision, hearing, and fitness benefits?
Your answers will help narrow your choices considerably.
Remember: The best Medicare coverage is not necessarily the plan with the most advertised benefits. It is the coverage that works best for your circumstances.
Step 2: Understand Your Main Medicare Coverage Options
Before comparing individual plans, determine which Medicare coverage approach makes the most sense for you.
Original Medicare With a Medicare Supplement
Original Medicare includes Part A (hospital insurance) and Part B (medical insurance).
You can add a Medicare Supplement insurance policy to help pay certain out-of-pocket expenses. You may also need a separate Medicare Prescription Drug Plan.
This approach may appeal to people who:
- Want access to doctors and hospitals nationwide that accept Medicare.
- See specialists frequently or have ongoing medical needs.
- Prefer not to rely on a Medicare Advantage provider network.
- Want more predictable medical expenses.
- Are comfortable paying a monthly Supplement premium.
Medicare Supplement policies generally do not include outpatient prescription drug coverage, and they typically do not include routine dental, vision, or hearing benefits.
Medicare Advantage
Medicare Advantage plans are offered by private insurance companies approved by Medicare. They provide your Medicare Part A and Part B benefits, and many include prescription drug coverage.
This approach may appeal to people who:
- Prefer lower monthly plan premiums.
- Are comfortable using a provider network.
- Want medical and prescription drug coverage combined in one plan.
- Value additional benefits, such as dental, vision, hearing, or fitness coverage.
- Are comfortable paying copayments or coinsurance when receiving services.
Medicare Advantage plans have an annual maximum out-of-pocket limit for covered Part A and Part B services. However, plan networks, cost-sharing requirements, and benefits can change from year to year.
Neither approach is automatically better. Your healthcare needs, financial situation, and personal preferences should guide the decision.
Step 3: Compare Total Costs — Not Just Monthly Premiums
A Medicare plan with a $0 monthly premium is not necessarily the least expensive choice.
When comparing coverage, consider:
- Monthly premiums: What will you pay for your Medicare coverage each month?
- Deductibles: How much must you pay before certain coverage begins?
- Copayments: What will you pay for doctor visits, specialists, hospital stays, and other services?
- Coinsurance: What percentage of covered service costs are you responsible for?
- Maximum out-of-pocket limit: For Medicare Advantage, what is the most you could pay annually for covered medical services subject to that limit?
- Prescription drug expenses: What will your medications cost throughout the year?
For a meaningful comparison, consider both your expected annual spending and what you could owe if you experience an unexpected illness or hospitalization.
Remember that most beneficiaries continue paying their Medicare Part B premium even when enrolled in a Medicare Advantage plan.
Step 4: Check Your Doctors and Hospitals
A Medicare plan may look attractive on paper but become a poor choice if it does not provide suitable access to your preferred healthcare providers.
Before choosing a Medicare Advantage plan, verify:
- Whether your primary care physician participates in the plan’s network.
- Whether your specialists are in-network.
- Whether your preferred hospital participates.
- Whether referrals or prior authorization are required for certain services.
- Whether and how out-of-network care is covered.
This is especially important in Minnesota, where access to healthcare providers can vary considerably between communities.
A plan that works well in the Twin Cities may not be as practical for someone receiving care in Ely, Virginia, Hibbing, or another northern Minnesota community.
Do not assume that because a doctor accepts Medicare, the doctor participates in every Medicare Advantage plan.
Tip: Verify provider participation directly with both the insurance company and the provider’s office before enrolling.
Step 5: Review Prescription Drug Coverage Carefully
Prescription drug coverage can significantly affect your total annual healthcare expenses.
When comparing plans, examine:
- Whether your medications are included on the plan’s covered drug list, called a formulary.
- Which cost-sharing tier applies to each medication.
- Whether prior authorization, quantity limits, or step therapy requirements apply.
- Whether your preferred pharmacy participates in the network.
- Whether another participating pharmacy offers lower costs.
A plan with a low premium may have substantially higher prescription expenses than another plan.
You can compare estimated annual medication costs using the official Medicare Plan Finder at Medicare.gov.
Step 6: Narrow Your Choices to Two or Three Plans
You do not need to compare every available plan in detail.
Once you have identified the coverage approach you prefer, eliminate options that do not meet your essential requirements.
For example, eliminate a plan if:
- Your essential healthcare providers are not accessible under its coverage rules.
- Important prescriptions are not covered, or the restrictions and costs are unacceptable.
- Its potential out-of-pocket expenses exceed your financial comfort level.
- Its provider network does not fit your travel or living arrangements.
Then compare the remaining two or three plans side by side.
Focus on the differences that will actually affect you.
A $10 difference in monthly premiums may be far less important than a substantial difference in hospital costs, prescription coverage, or access to a preferred specialist.
Step 7: Review Your Coverage Every Year
Even if you are satisfied with your current Medicare coverage, reviewing it annually is worthwhile.
Insurance companies may change:
- Monthly premiums and deductibles.
- Copayments and coinsurance.
- Provider and pharmacy networks.
- Prescription drug formularies.
- Additional benefits.
- Plan availability in your county.
If you have Medicare Advantage or a Medicare Prescription Drug Plan, review your Annual Notice of Change to understand what will be different next year.
For 2027 coverage, the Medicare Annual Enrollment Period runs from October 15 through December 7, 2026. Changes made during this period generally take effect January 1, 2027.
If you are considering switching from Medicare Advantage to Original Medicare with a Medicare Supplement, investigate Supplement eligibility before making a change. You may not have guaranteed access to every Supplement policy. Federal and Minnesota guaranteed-issue rules can affect your options.
A Simple Medicare Plan Comparison Checklist
Before making a decision, ask yourself:
- Have I identified my most important healthcare needs?
- Have I compared Medicare Advantage with Original Medicare and a Medicare Supplement?
- Have I considered total annual costs rather than premiums alone?
- Have I checked my preferred doctors and hospitals?
- Have I reviewed my prescription drug coverage?
- Have I considered my financial exposure if I need significant medical care?
- Have I narrowed my options to a manageable number?
- Do I understand the important tradeoffs of my preferred coverage?
If you can answer these questions confidently, you are much closer to making an informed Medicare decision.
You Don’t Have to Figure It Out Alone
Comparing Medicare plans should be about understanding your options, not becoming an insurance expert.
At YourMedicareMN, we believe education comes before enrollment.
Visit Contact Us to schedule a personalized Medicare review and get answers tailored to your situation.
For official Medicare information, visit the Medicare.gov website.
YourMedicareMN is not connected with or endorsed by the U.S. government or the federal Medicare program. Plan availability and benefits vary by location and plan. Contact the plan or Medicare for complete plan information.
Learn First. Decide With Confidence.
YourMedicareMN
Medicare Guidance for Minnesotans